Understanding Physical Gold Investments: A Practical Guide to Buying Bullion
Kelvin Bratton2026-09-20
Gold has served as a store of wealth for over 5,000 years, surviving the collapse of empires, currencies, and financial systems. While stocks lose 90% of their value and fiat currencies gradually erode through inflation, gold retains purchasing power across generations. If you're considering adding physical gold to your portfolio, you need to understand what you're actually buying, how pricing works, and what separates investment-grade bullion from collectibles.
Why Investors Choose Physical Gold Over Paper Alternatives
Physical gold offers something that ETFs, mining stocks, and futures contracts can't: direct ownership with no counterparty risk. When you hold a 1 oz American Gold Eagle or a PAMP Suisse bar, you own the metal outright. No bank, brokerage, or fund manager stands between you and your asset.
According to the World Gold Council, physical gold demand reached 4,741 tonnes in 2023, with investment demand accounting for 1,217 tonnes. That's not speculative hype. It's people buying tangible assets they can store in a safe or vault.
The advantage becomes clear during financial stress. When Bear Stearns collapsed in 2008, investors holding paper gold through the firm lost access to their positions overnight. Physical gold holders faced no such risk. Your metal doesn't disappear when markets crash or institutions fail.
Physical gold also provides portfolio diversification that correlates negatively with stocks during market downturns. When the S&P 500 dropped 34% in early 2020, gold climbed 25% for the year. It won't protect you from every market move, but it historically performs differently than equity markets.
Investment-Grade Gold vs. Numismatic Collectibles
Not all gold products serve the same purpose. Investment-grade bullion is priced by weight and purity. Numismatic coins are priced by rarity, condition, and collector demand. The distinction matters enormously for your returns.
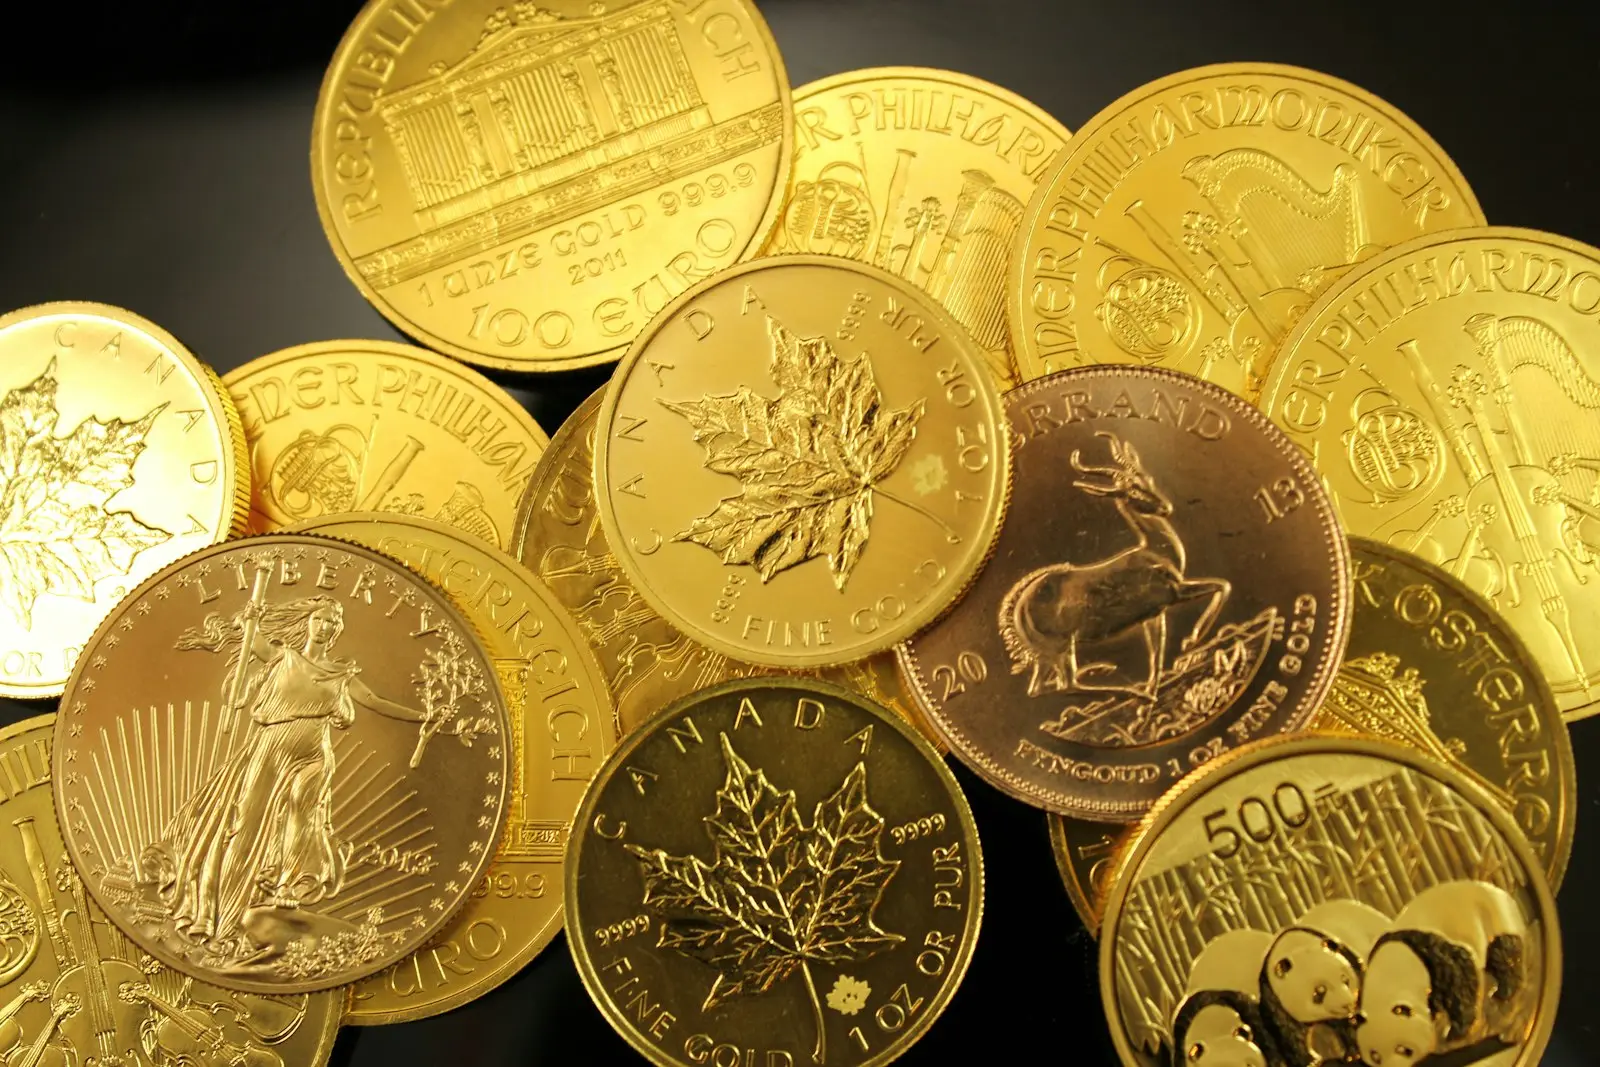
Investment-grade gold includes: - Government-minted coins like American Gold Eagles, Canadian Maple Leafs, and Austrian Philharmonics - Private mint bars from accredited refiners like PAMP Suisse, Credit Suisse, and Perth Mint - Any gold product that's .995+ fine (99.5% pure) for bars or .9999 fine (99.99% pure) for coins
These products trade based on their gold content. A 1 oz bar contains one troy ounce of gold regardless of which mint produced it. You pay spot price plus a small premium for manufacturing and distribution.
Numismatic coins work differently. A rare 1933 Saint-Gaudens Double Eagle sold for $18.9 million at auction in 2021, despite containing only about $2,000 worth of gold at the time. The remaining $18.898 million came from collector value. That's fine if you're a numismatist. It's terrible if you want liquid gold that's easy to sell at fair value.
Understanding Spot Price and Premiums
Spot price is the current global market price for one troy ounce of pure gold, determined by futures trading on exchanges like COMEX in New York and LBMA in London. It's listed 24 hours a day, five days a week. As of this writing, spot price fluctuates based on real-time supply and demand.
But you can't actually buy gold at spot price. Physical delivery requires minting, quality assurance, shipping, insurance, and dealer operations. The difference between spot price and your purchase price is the premium.
Premiums vary by product type: - Government coins typically carry 3-6% premiums over spot. American Gold Eagles generally cost more than Canadian Maple Leafs because of higher U.S. demand. - Private mint bars usually offer lower premiums, often 2-4% over spot. A 1 oz gold bar from a random accredited mint can be the most cost-effective option. - Larger bars reduce premiums further. A 10 oz bar might carry only 1-2% premium over spot since minting costs get spread across more ounces.
According to the U.S. Mint, production of American Gold Eagles totaled 1,063,000 ounces in fiscal year 2023. High demand keeps premiums elevated compared to less popular alternatives.
One pricing structure stands out: transparent, itemized fees shown upfront. Liberty Gold Silver provides written documentation of every fee before purchase. You know exactly what you're paying for the metal, what covers minting, and what goes toward logistics. This contrasts with dealers who written price "all-in" prices without breaking down the components. Hidden fees inflate costs without improving the product you receive.
American Gold Eagles: The Most Recognized U.S. Bullion Coin
The American Gold Eagle was authorized by the Gold Bullion Coin Act of 1985 and first minted in 1986. It's the official gold bullion coin of the United States, produced by the U.S. Mint with gold mined domestically.
The coin contains 91.67% gold (22 karat), with the remainder being silver and copper for durability. A 1 oz American Gold Eagle actually weighs 1.0909 troy ounces but contains exactly one troy ounce of pure gold. The alloy makes it more scratch-resistant than 24-karat coins.
Why do investors pay premium prices for Eagles? - Legal tender status: Each coin has a $50 face value (though gold content is worth far more) - Universal recognition: Dealers worldwide know this product and buy it without verification delays - IRA eligibility: Meets IRS purity requirements for Self-Directed IRAs - Guaranteed weight and purity: U.S. government backing provides confidence in authenticity
The downside is cost. American Gold Eagles typically carry 4-6% premiums over spot price, higher than most alternatives. You pay for the U.S. Mint's brand recognition and sovereign guarantee.
These coins work best for investors who value liquidity and plan to sell quickly when needed. The global recognition means you'll find buyers anywhere, often at competitive buyback prices. If you're holding for decades and prioritize low acquisition costs, bars might make more sense.
Gold Bars: Lower Premiums for Weight-Focused Investors
Gold bars are produced by private refiners rather than government mints. They range from 1 gram to 400 oz (the "Good Delivery" bar standard), with 1 oz, 10 oz, and 1 kilo being popular investment sizes.
Bars from accredited refiners meet the same purity standards as government coins, but they cost less to produce. No intricate designs, no collectibility factors. Just refined gold stamped with weight, purity, refiner mark, and serial number.
A 1 oz gold bar from a recognized mint like PAMP Suisse or Perth Mint typically costs 2-4% over spot. That's $40-80 less per ounce than an American Gold Eagle when gold is $2,000/oz. The savings compound quickly: - 10 oz in bars: Save $400-800 - 50 oz in bars: Save $2,000-4,000 - 100 oz in bars: Save $4,000-8,000
Bars trade liquidity for cost savings. While reputable dealers buy back gold bars readily, they may test purity before purchase since bars lack sovereign guarantees. This adds time to the selling process. High-profile refiners like PAMP Suisse with distinctive security features minimize this friction.
For IRA purposes, gold bars must meet .995+ fineness standards. Most investment-grade bars exceed this at .9999 fine. Liberty Gold Silver verifies IRA eligibility on every product page, so you don't have to interpret IRS regulations yourself.
IRS-Approved Gold for Self-Directed IRAs
The IRS allows physical gold in Self-Directed IRAs under strict purity requirements. Gold must be .995+ fine (99.5% pure) to qualify. This excludes most pre-1933 U.S. gold coins and many historical pieces that don't meet modern refinement standards.
Approved gold products include: - American Gold Eagles (despite being 22-karat, they're specifically exempted) - Canadian Gold Maple Leafs (.9999 fine) - Austrian Gold Philharmonics (.9999 fine) - Gold bars from COMEX-approved refiners (.999+ fine) - Australian Gold Kangaroos (.9999 fine)
According to IRS Publication 590-B, the physical metal cannot be stored at home. It must be held by an IRS-approved custodian in a qualified depository. You own the metal, but you don't possess it until you take a distribution.
This creates three parties in every IRA gold transaction: 1. The dealer (who sells you the metal) 2. The custodian (who administers your IRA account) 3. The depository (who stores the physical gold)
Each party charges separate fees. Custodians typically charge $75-300 annually for account administration. Depositories charge $100-250 annually for segregated storage. These ongoing costs matter over decades.
Storage Options: Home, Bank, and Professional Depositories
Once you own physical gold, you need to store it securely. Three primary options exist, each with tradeoffs:
Home Storage
Storing gold at home gives you immediate access and eliminates storage fees. Many investors keep 1-5 oz at home for liquidity while storing larger holdings elsewhere.
Requirements for safe home storage: - A high-quality safe (preferably fire-rated and floor-bolted) - Homeowner's insurance rider covering precious metals - Minimal disclosure (don't advertise your holdings) - Secure location unknown to service workers, contractors, and casual visitors
Homeowner's insurance typically covers only $200-500 in precious metals under standard policies. You need to add a rider specifically listing gold and silver. Annual costs run 1-2% of the insured value.
Home storage prohibits IRA-held gold. Once you take a distribution from your IRA, it's no longer retirement money, and you'll owe taxes on the distribution.
Bank Safe Deposit Boxes
Safe deposit boxes at banks cost $60-300 annually depending on size and location. They provide security without the risk of home burglary.
The drawbacks: - Limited access during bank hours only - No insurance coverage (banks don't insure box contents) - Potential government seizure (precedent exists from Executive Order 6102 in 1933) - Bank failure risks, though FDIC protects deposits, not box contents
You'll need separate insurance for metals in a bank box, which negates much of the cost advantage over professional depositories.
Bonded Depositories
Professional depositories are IRS-approved facilities specifically designed for precious metals storage. They provide: - Full insurance coverage included in fees - Segregated storage (your specific bars, not pooled metal) - Regular audits and inventory verification - 24/7 security with armed response - Access during normal business hours for viewing or taking delivery
According to the Brink's Global Services 2024 report, their depositories handle over $30 billion in precious metals annually. These aren't casual operations. They're purpose-built vaults with insurance underwritten by Lloyd's of London.
Annual storage fees run $100-250 for typical retail accounts. That buys physical security that exceeds what most individuals can achieve at home, plus comprehensive insurance that actually pays claims.
Liberty Gold Silver works with Delaware Depository, one of the largest independent depositories in the U.S. Fees are disclosed upfront, and you can arrange to view your metal or take physical delivery with reasonable notice.
How to Verify Gold Authenticity
Gold counterfeiting exists, primarily with bars rather than coins. Tungsten-filled bars surfaced in 2012, taking advantage of tungsten's similar density to gold. Smart buying practices and verification tools protect against fakes.
Buy from established dealers with verifiable track records. Liberty Gold Silver sources from accredited mints only: U.S. Mint, Royal Canadian Mint, Perth Mint, PAMP Suisse, and other LBMA-approved refiners. These institutions have supply chain controls that prevent counterfeits from entering their products.
For additional verification: - Electronic testing: XRF analyzers scan metal composition without damage. Professional dealers use these during buyback transactions. - Dimensional testing: Precision calipers verify exact measurements. Tungsten cores alter dimensions slightly. - Weight and ping testing: Genuine gold has a distinctive ring when struck. Counterfeit cores sound different. - Sigma Metalytics: Measures electrical conductivity to confirm gold purity through the entire bar, not just surface.
Government coins are harder to fake profitably. The intricate designs, edge reeding, and security features cost more to replicate than the potential profit margin. Bars, being simpler, attract more counterfeiting attempts.
If you're buying older bars or coins from secondary markets, insist on dealer verification before payment. Reputable dealers test everything as a matter of policy.
When to Sell Physical Gold
Gold is a long-term asset, not a day-trading vehicle. Transaction costs from premiums on purchase and bid-ask spreads on sale make frequent trading unprofitable. Most investors hold gold for 5-20+ years, selling during specific circumstances:
Portfolio rebalancing: If gold appreciates from 10% to 20% of your portfolio, selling excess back to 10% maintains your target allocation.
Major price peaks: Gold hit $2,075 in August 2020 and again in March 2022. Long-term holders who bought below $1,500 saw 30%+ gains and could lock in profits.
Financial emergencies: Physical gold provides liquidity when you need it. Reputable dealers buy back their products at current market rates, typically within 1-2 business days.
Estate planning: Heirs may prefer liquid assets to physical metals. Selling before death simplifies estate distribution.
Buyback pricing varies by dealer. Many charge 2-5% below spot when purchasing your gold. That's the bid-ask spread. If spot price is $2,000/oz, you might receive $1,900-1,960 per ounce depending on product type and dealer policies.
Tax Implications of Selling Gold
The IRS classifies gold as a collectible, not a regular investment asset. This creates higher tax rates on gains:
Long-term capital gains: Gold held over one year is taxed at 28% maximum rate, significantly higher than the 15-20% rates for stocks and bonds.
Short-term gains: Gold held under one year is taxed as ordinary income at your marginal rate, which can reach 37% federally.
State taxes: Most states add their own capital gains taxes on top of federal rates.
For example, if you bought 10 oz of gold at $1,500/oz ($15,000 total) and sold at $2,000/oz ($20,000 total), your capital gain is $5,000. At the 28% collectibles rate, you'd owe $1,400 in federal taxes, plus state taxes in most locations.
IRA-held gold avoids these issues. Gains inside a Traditional IRA aren't taxed until distribution, and then they're taxed as ordinary income regardless of asset type. Roth IRAs avoid taxation entirely on qualified distributions.
You're required to report gold sales on Form 8949 and Schedule D of your tax return. Dealers issue 1099-B forms for reportable transactions (generally involving large quantities or multiple sales totaling over specific thresholds).
Market Timing and Dollar-Cost Averaging
Gold prices fluctuate based on inflation expectations, currency movements, geopolitical stress, and real interest rates. Trying to time the perfect entry creates as much risk as opportunity.
According to data from Macrotrends, gold averaged $1,770/oz in 2023 with an intraday range from $1,810 to $2,135. That's 18% volatility. Waiting for the "right" price means potentially missing sustained uptrends or buying near peaks.
Dollar-cost averaging reduces timing risk. Instead of investing $50,000 at once, you buy $5,000 monthly for ten months. You'll buy more ounces when prices dip and fewer when they spike. Over time, this averages out emotional decision-making.
Historical data supports consistent accumulation. From 2000 to 2023, gold averaged 9.7% annual returns despite multiple boom-bust cycles. Investors who bought consistently throughout the period captured those gains. Those who tried timing entries often bought during euphoric peaks and sold during fearful bottoms.
Long-term holders focus on purchasing power preservation rather than price speculation. Gold won't make you wealthy, but it maintains wealth across decades and generations.
Getting Started with Physical Gold Investment
If you're ready to add physical gold to your portfolio, start with clear objectives. Are you hedging against currency risk? Diversifying from stocks? Preparing for retirement? Your goals determine product selection and allocation size.
Most financial advisors suggest 5-15% of total investable assets in precious metals. That's enough for meaningful diversification without overconcentration in a non-yielding asset.
For new buyers, consider this approach: 1. Start with 1-5 oz of gold coins or bars to familiarize yourself with the product and process 2. Choose IRA-eligible products if you're buying for retirement 3. Compare total costs, not just product premiums (include shipping, insurance, and potential storage) 4. Verify every fee in writing before purchase 5. Plan for long-term holding, typically 5+ years minimum
Most importantly, you receive written documentation of all fees before finalizing your purchase. No surprises, no hidden charges discovered later. That's not standard practice across the industry, but it should be.
Physical gold is straightforward once you understand the fundamentals. You're buying weight and purity, storing it securely, and holding it for long-term wealth preservation. Everything else is detail work that becomes clear with experience.
- World Gold Council. "Gold Demand Trends Full Year 2023." https://www.gold.org/goldhub/research/gold-demand-trends
- U.S. Mint. "2023 Annual Report." https://www.usmint.gov/about/annual-report
- IRS Publication 590-B. "Distributions from Individual Retirement Arrangements (IRAs)." https://www.irs.gov/publications/p590b
- Brink's Global Services. "2024 Precious Metals Storage Report." https://www.brinks.com
- Macrotrends. "Gold Prices - 100 Year Historical Chart." https://www.macrotrends.net/1333/historical-gold-prices-100-year-chart
- Liberty Gold Silver. "Guide to Precious Metals." https://www.libertygoldsilver.com/learn/precious-metals
- Liberty Gold Silver. "IRS-Approved Precious Metals for IRAs." https://www.libertygoldsilver.com/precious-metals/ira-eligible
- Liberty Gold Silver. "What Is Spot Price in Precious Metals?" https://www.libertygoldsilver.com/learn/spot-price
This article is educational. It is not a recommendation to buy or sell anything, and it does not consider your circumstances. Prices can move in either direction.